How long does it take to buy a house in San Diego? Most buyers need about 60 to 90 days from their first lender conversation to receiving the keys. The bigger variable is the home search, which can take anywhere from two weeks to several months. Once your offer is accepted, the San Diego home buying process usually moves in a predictable 30 to 45 days through inspection, appraisal, escrow, and closing.
That 60 to 90 day window is an average, not a promise. A cash buyer who finds the right condo quickly can close in a couple of weeks. A first-time buyer who is still saving, comparing neighborhoods, and competing against other offers may spend six months or more. This guide breaks down every stage of the buying a home timeline, explains what typically happens in each one, and shows what speeds up or slows down a San Diego real estate closing.
If you are still deciding whether to buy at all, our guide on why you should buy a home vs. rent is a good place to start. If you are ready to move, read on and use the timeline below to plan your dates, your budget, and your move.
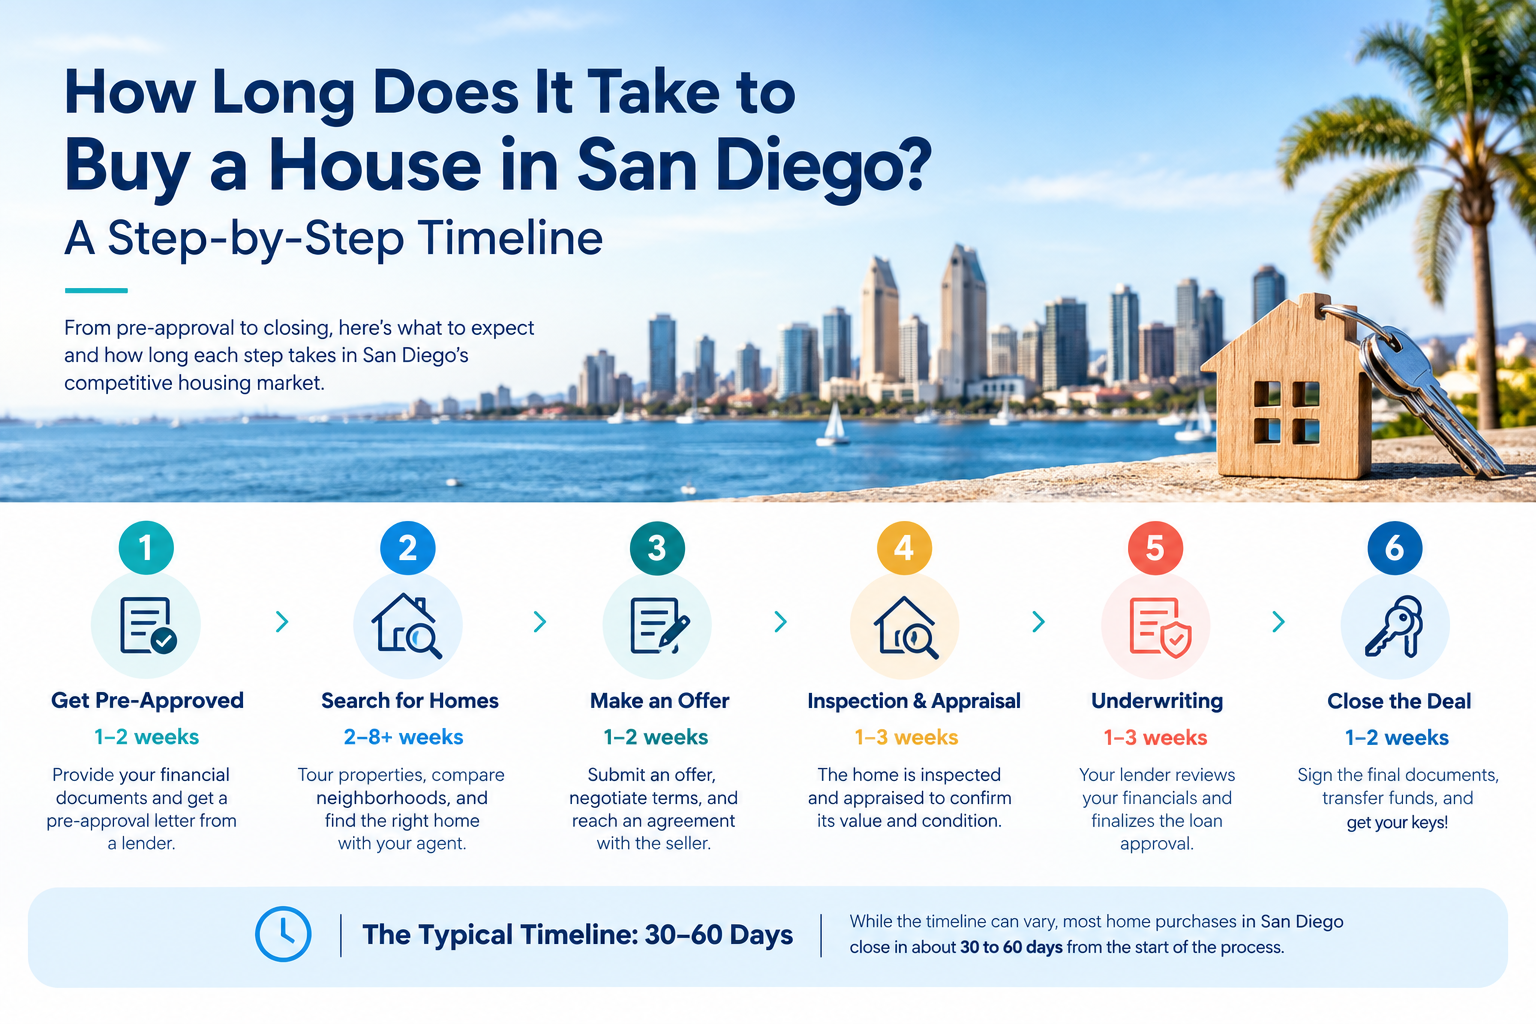
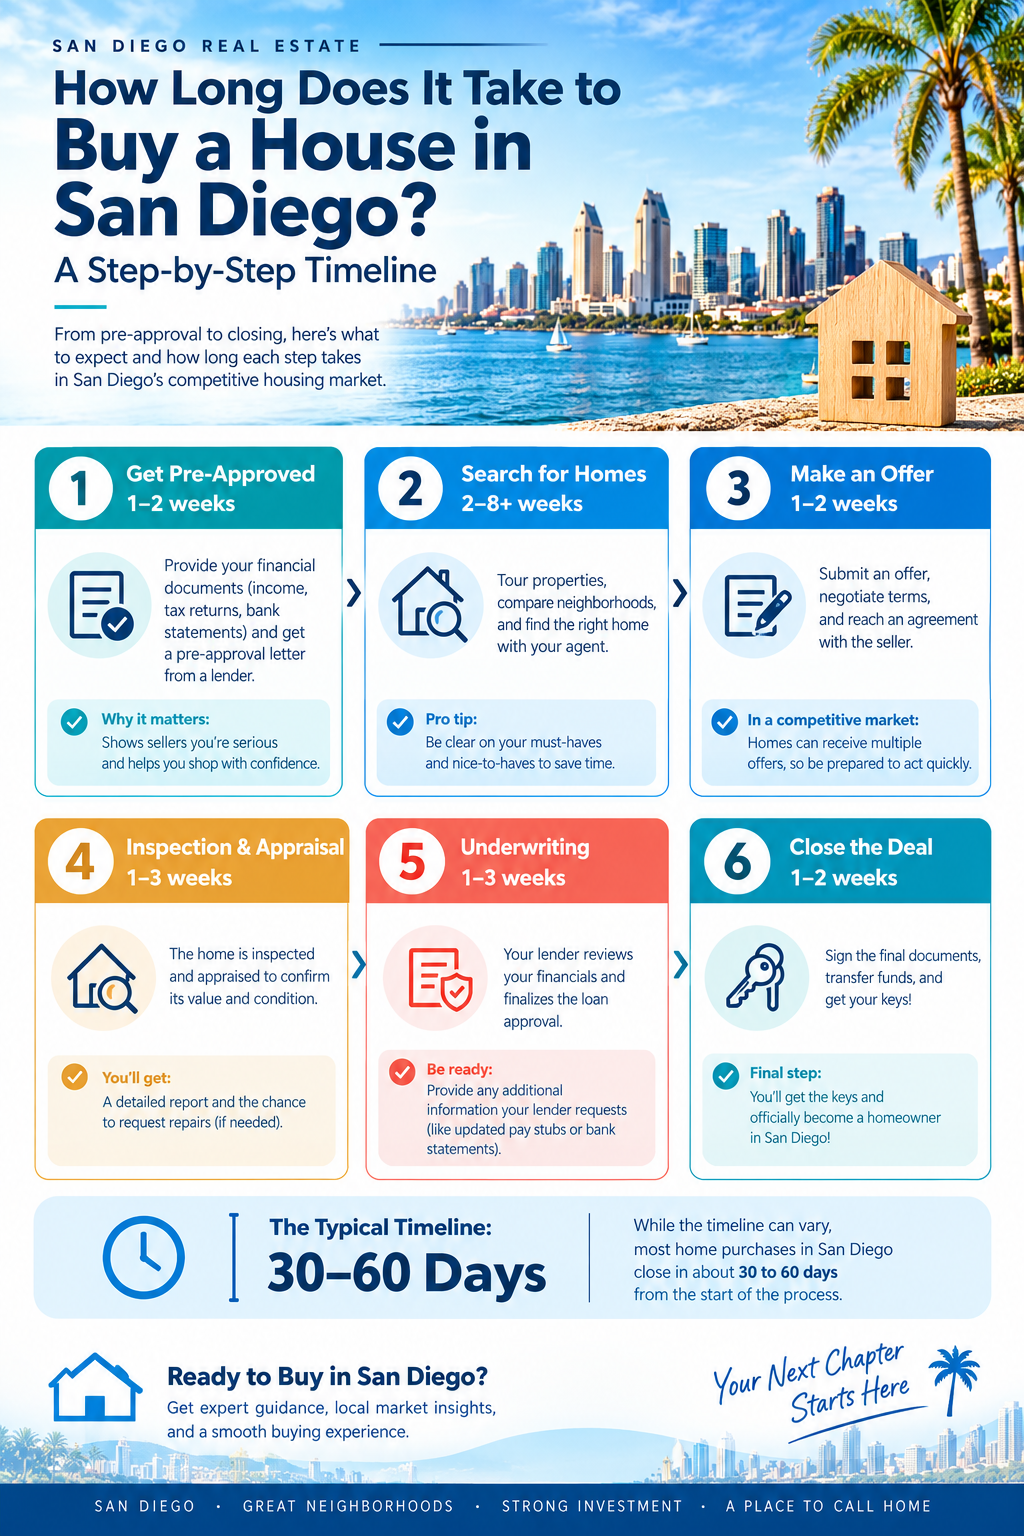
Quick answer: Buying a house in San Diego typically takes 60 to 90 days overall. Pre-approval takes 1 to 2 weeks, the home search 2 to 8+ weeks, offer and negotiation 1 to 2 weeks, escrow 21 to 30+ days, and the final closing steps 1 to 3 days. Cash purchases can close in as little as 7 to 14 days, while complicated financing or repairs can stretch escrow well beyond 45 days. Work with a local agent to keep every step on schedule.
San Diego Home Buying Timeline at a Glance
Before diving into the details, here is the full timeline in one place. Use it to see where you are today and how many weeks remain before you can move in. Each stage is explained below, and if you want a shortcut to planning your own dates, Adam Kelley can build a custom schedule around your goals and your lender’s requirements.
| Stage | Typical Time | What Happens |
|---|---|---|
| 1. Mortgage pre-approval | 1–2 weeks | Gather tax returns, pay stubs, and bank statements; the lender issues a pre-approval letter. |
| 2. Home search | 2–8+ weeks | Tour homes, compare neighborhoods, and narrow your list with your agent. |
| 3. Offer and negotiation | 1–2 weeks | Submit an offer; the seller accepts, rejects, or counters. |
| 4. Escrow (inspection, appraisal, underwriting) | 21–30+ days | Deposit earnest money, complete inspections, appraisal, and loan approval. |
| 5. Closing | 1–3 days | Sign loan documents, funds are wired, the deed is recorded, and you get the keys. |
| Total | About 60–90 days | Faster for cash buyers, slower in competitive or complex situations. |
Notice that only the escrow and closing stages are mostly fixed once you are under contract. The stages before that are where you have the most control. Prepare early, and you can shave weeks off your buying a home timeline. Our first-time home buyer guide walks through the same stages with extra detail for beginners.
Step 1: Get Ready and Get Pre-Approved (1–2 Weeks)
The San Diego home buying process starts before you look at a single listing. Your first job is to understand what you can afford and prove it to sellers. A mortgage pre-approval is the document that does both, and it is required by nearly every listing agent before they will take your offer seriously. Getting it done quickly keeps the rest of your timeline on track, so start with our guide to how much house you can afford in San Diego.
Gather your financial documents
Lenders typically ask for two years of tax returns and W-2s, recent pay stubs, two months of bank statements, and identification. Self-employed buyers usually need profit-and-loss statements and additional tax documents. The faster you deliver a complete package, the faster you receive your letter. Missing paperwork is the most common reason pre-approval drags past two weeks, and our real estate documents checklist shows which records to keep organized before and after you buy.
Pre-qualification vs. pre-approval
A pre-qualification is a quick estimate based on information you provide. A pre-approval involves a credit check and document review, so it carries real weight with sellers. In San Diego’s competitive market, a pre-approval letter from a reputable lender can be the difference between an accepted offer and a rejected one. Ask your agent for lender recommendations, and read our advice on how to choose a realtor who has strong lender relationships.
Set your budget and down payment
Pre-approval tells you the maximum a lender will approve, but your comfortable budget may be lower. Consider your monthly payment, property taxes, insurance, HOA dues, and cash needed for closing. Buyers who set a realistic budget before touring homes waste less time on properties they cannot afford. Review the closing costs buyers pay in San Diego so your savings target includes more than the down payment.
Step 2: Search for Your Home (2–8+ Weeks)
The home search is the least predictable part of buying a house in San Diego. Inventory can be tight, especially for well-priced homes in desirable neighborhoods, and a good listing may receive multiple offers within days. Some buyers find the right property in two weeks. Others tour for several months. Your flexibility on price, location, and features usually determines which group you fall into, and a local agent can help you find the right fit faster.
Define your must-haves and nice-to-haves
Before you tour, separate the non-negotiables from the wish list. Bedrooms, commute, school district, and budget are usually must-haves. A pool, a view, or a renovated kitchen may be nice to have. A shorter must-have list widens your options and speeds up the search. If you are torn between areas, our comparison of Carlsbad, Oceanside, and Escondido shows how North County neighborhoods differ on price, lifestyle, and commute.
Tour homes efficiently
Set aside specific days each week for showings, and be ready to see new listings the day they hit the market. Bring a checklist so you can compare homes objectively instead of relying on memory. Our home viewing checklist covers the details worth inspecting during a tour, from roof condition to water pressure. Taking notes and photos saves time when you narrow the field.
What about rent-to-own homes in San Diego?
Some buyers who are not ready for a traditional mortgage look at rent to own houses in San Diego as a bridge. In a rent-to-own agreement, you rent the home for a set period with an option to buy later. It can add months or years to your path to ownership, and the terms vary widely, so read every clause carefully. We explain the risks and benefits in our guide to rent-to-own homes in San Diego. If you are also weighing rental options while you save, see how to find private landlords safely.
Step 3: Make an Offer and Negotiate (1–2 Weeks)
Once you find the right home, your agent will help you write an offer. The offer includes your price, earnest money deposit, financing terms, contingencies, and proposed closing date. In a hot market, sellers may respond within hours, while a slower market can involve a few days of back-and-forth. Your agent’s negotiation skill matters here, and our guide on choosing the right real estate agent explains what to look for.
Seller responses: accept, reject, or counter
Sellers have three options. They can accept your offer, reject it, or send a counteroffer with different terms. Each counter can add a day or two. If the seller accepts, you are officially “in contract,” and your escrow clock begins. If you are new to this stage, review the pros and cons of purchasing a property so you know which terms are worth negotiating.
How multiple offers affect the timeline
When several buyers compete, sellers often set a deadline and review all offers at once. This can shorten your wait but lengthen your search if you lose out. Buyers with a strong pre-approval, a reasonable inspection window, and a flexible closing date often stand out. Your agent can also advise on whether to include an appraisal or loan contingency, and the top San Diego agents are known for strategies that keep buyers competitive without taking unnecessary risk.
Step 4: Escrow Begins (21–30+ Days)
Escrow is the stretch between an accepted offer and the day you receive the keys, and it is the most structured part of the San Diego real estate closing. A neutral escrow company holds funds and documents while everyone completes their tasks. Most financed purchases take about 30 days, though many run 30 to 45 days when repairs, appraisal issues, or lender conditions come up. Understanding each task helps you avoid surprises, and you can ask us any time how your escrow is progressing.
Open escrow and deposit earnest money
Within a few days of acceptance, you will open escrow and deliver your earnest money deposit. This shows good faith and is credited toward your purchase. Missing the deadline can put the contract at risk, so treat it as a top priority. The deposit is one of several upfront expenses, and our breakdown of San Diego closing costs explains what else to prepare for.
Home inspection (about 1–2 weeks)
Most buyers schedule a general home inspection within the first week or two of escrow. Inspectors examine the roof, foundation, plumbing, electrical, HVAC, and more. You may also order specialty inspections for termite, sewer line, pool, or roof. If problems appear, you can negotiate repairs, request credits, or in some cases cancel under your contingency. Bring the home viewing checklist to compare your own notes to the inspector’s findings.
Appraisal (about 1–3 weeks)
Your lender will order an appraisal to confirm that the home is worth the price you agreed to pay. Appraisers visit the property, review comparable sales, and submit a report. Scheduling and report delivery can take one to three weeks depending on demand. If the value comes in below your price, you may need to renegotiate, bring extra cash, or challenge the value. Learn more about the process in our article on what an appraiser does.
Loan underwriting and approval
While inspections and appraisal happen, your lender’s underwriter reviews your finances, the appraisal, and the property’s title. They may request additional documents, so respond quickly. Do not open new credit cards, change jobs, or make large purchases during this time, because any change can delay or derail approval. The final green light is called “clear to close,” and staying in touch with your agent and lender is the best way to keep your loan on track.
Disclosures, title, and contingency removal
California sellers must provide a set of disclosures, and buyers typically review them alongside the preliminary title report. In standard California purchase contracts, contingencies for inspection, appraisal, and loan approval are often set at around 17 days, though they can be shorter or longer by agreement. As you complete each item, you sign contingency removals. Your agent will help you review each document and protect your interests at every step.
Step 5: Closing Day and Getting Your Keys (1–3 Days)
The final stretch of a San Diego real estate closing is short but important. Roughly three business days before closing, you will receive your Closing Disclosure and review the final numbers. You will then sign your loan documents, and the lender funds the loan. The deed is recorded with the county, and you receive your keys, often on the same day or the following morning. Our list of essential real estate documents after closing explains what to keep once you own the home.
Final walk-through
Within a few days before closing, you will do a final walk-through to confirm that the home is in the agreed condition and that any negotiated repairs are complete. This is your chance to catch problems before you sign. Test appliances, run faucets, and check that nothing has been removed. If something is wrong, tell your agent immediately so it can be fixed before the deal funds. Ask your agent to schedule it early so there is time to resolve issues.
Sign, fund, and record
At signing, you will bring your ID and any remaining funds, usually by wire or cashier’s check. Always verify wire instructions by phone with your escrow officer to avoid fraud. Once your lender funds and the county records the deed, you are officially the owner. Closing costs are due at this stage, so review the closing costs guide one more time before you sign.
Sample San Diego Buying Timelines
Real-life timelines vary, but these three examples show how different buyers experience the process. Use them to estimate your own schedule, and contact Adam Kelley if you want a personalized timeline.
- Prepared financed buyer (about 60 days): Pre-approved before searching, tours for three weeks, has an offer accepted in week four, and closes 30 days later.
- First-time buyer with a longer search (about 90 to 120 days): Spends a few weeks getting documents and credit in order, tours for six to eight weeks, loses one bid, then closes after a 30 to 35 day escrow. Our first-time buyer guide is built for this path.
- Cash buyer (about 2 to 4 weeks after an accepted offer): Skips underwriting and often the appraisal, which can shorten closing dramatically. See the pros and cons of buying with cash.
What Can Speed Up Your Home Purchase?
You cannot control the market, but you can control your preparation. These strategies help buyers move faster without cutting corners, and a good agent can help you apply them.
- Get pre-approved early. Have your letter in hand before your first showing.
- Organize your documents. Send your lender everything on the first request, and respond to follow-up questions the same day.
- Choose a responsive team. An agent, lender, and escrow officer who communicate quickly prevent small delays.
- Schedule inspections immediately. Book inspectors as soon as your offer is accepted. See our home viewing checklist for what to look for.
- Be flexible on closing date. Matching the seller’s preferred timeline can make your offer more attractive.
- Keep your finances stable. Avoid new debt or job changes until after closing.
If you are buying with cash or a large down payment, you may be able to compress the timeline even further. Weigh that speed against the added risk of skipping inspections or appraisals, and read our cash buying pros and cons before deciding.
What Can Delay Buying a House in San Diego?
Delays are common and often avoidable. Knowing the main causes lets you plan ahead and build a buffer into your schedule. If a delay does occur, your agent can help you solve it before it puts the deal at risk.
- Low appraisal. A valuation below the purchase price can force renegotiation or extra cash at closing.
- Loan issues. Missing documents, changes in income, or new debt can slow underwriting or cause denial.
- Inspection surprises. Major repair needs can lead to renegotiation, seller credits, or new bids. Read the pros and cons of purchasing a property to know what to expect.
- Title problems. Liens, boundary disputes, or ownership questions can take time to resolve.
- Seller delays. Slow disclosures, repairs, or move-out timing can push back closing.
- HOA paperwork. Condo and townhome buyers often wait on HOA documents.
- Slow communication. Missed signatures and late replies add days that were never on the calendar.
Most delays are manageable if they are caught early. Ask your agent for weekly updates during escrow, and tell your lender immediately if anything changes in your finances. Clear communication is the simplest way to protect your closing date, which is why we recommend reading how to choose a realtor who communicates well.
Does the Timeline Change by San Diego Area?
Yes, to a degree. Coastal and central neighborhoods often have faster-moving listings and more competition, so the search phase can take longer for buyers with strict criteria. North County cities, including Carlsbad, Oceanside, and Escondido, offer a wider range of price points and property types, which can widen your options. Condos add HOA document review, and older homes may need extra inspections. Your agent’s local knowledge helps you set the right expectations for the neighborhood you have in mind.
Step-by-Step Checklist to Stay on Schedule
- Week 1–2: Gather documents, check your credit, and get pre-approved. Start with the affordability guide.
- Week 2–3: Hire your agent, define your must-haves, and begin touring homes.
- Week 3–10: Tour, compare, and submit offers. Use the viewing checklist.
- Offer accepted: Open escrow, deposit earnest money, and schedule inspections right away.
- Escrow days 1–17: Complete inspections, review disclosures, and order the appraisal.
- Escrow days 17–30: Finish underwriting, remove contingencies, and receive clear to close.
- Closing week: Review the Closing Disclosure, do the final walk-through, sign, and get your keys. Keep your post-closing documents safe.
Explore More San Diego Home Buying Guides
A great buying experience is built on good information. These related guides from Adam Kelley Real Estate will help you prepare for each stage. Start with the first-time home buyer guide, then estimate your budget with our affordability breakdown and closing costs guide. If you are comparing areas, read about North County neighborhoods, and if you may sell one day, see how to hire the right listing agent.
Frequently Asked Questions About Buying a House in San Diego
How long does it take to buy a house in San Diego?
Most buyers take about 60 to 90 days from pre-approval to closing. The search can add weeks or months, while escrow typically takes 21 to 30 days or more. See the full San Diego home buying timeline.
How long does it take to close on a house in San Diego?
Once your offer is accepted, closing typically takes 30 to 45 days for financed purchases. Cash buyers can close in as little as 7 to 14 days. Learn what affects that window in our closing costs guide.
How long does mortgage pre-approval take?
Pre-approval usually takes one to two weeks, and sometimes a few days if your documents are organized. Providing complete tax returns, pay stubs, and bank statements speeds it up. Start with our affordability guide.
How long does the home search take in San Diego?
The search commonly takes 2 to 8 weeks, though it can be longer in tight inventory or for buyers with specific criteria. A local agent can help you move faster by setting up listing alerts and scheduling showings quickly.
What happens during escrow?
During escrow, a neutral third party holds funds while you complete inspections, the appraisal, loan underwriting, and title review. When every condition is met, the deal moves to closing. Read about the appraiser’s role.
Can I buy a house in San Diego in 30 days?
It is possible if you are pre-approved, find a home quickly, and have a short escrow, or if you pay cash. Most financed buyers need closer to 60 days overall. See our cash buying guide.
Are rent to own houses in San Diego a faster way to buy?
Not usually. Rent-to-own lets you move in sooner but delays ownership, often by a year or more, and terms vary widely. Learn the details in our rent-to-own guide.
What can delay closing on a house?
Common causes include low appraisals, loan documentation problems, inspection issues, title concerns, HOA paperwork, and slow communication. Staying responsive helps, and your agent can guide you.
Do I need a real estate agent to buy a house in San Diego?
You are not legally required to have one, but an agent helps you negotiate, meet deadlines, and avoid costly mistakes. Learn how to pick one in our guide on how to choose a realtor.
When should I start the home buying process?
Start about three to six months before you want to move, so you have time to organize finances, get pre-approved, and search without pressure. Reading the buy vs. rent guide is a smart first step.
Ready to Start Your San Diego Home Purchase?
Buying a home in San Diego typically takes about 60 to 90 days, but your timeline depends on how prepared you are and how quickly you find the right property. The best way to stay on schedule is to get pre-approved, work with a responsive local team, and understand every step before it happens. Adam Kelley Real Estate helps buyers across San Diego, Carlsbad, Oceanside, Escondido, and surrounding areas move from first questions to closing day with clear communication and local expertise.
Ready to plan your purchase? Contact Adam Kelley today to talk through your goals, timeline, and budget, and get a custom step-by-step plan for buying your next home.